Get the link to change the password

E-mail *

Send
Give up
logo
022 822 024

Assistment and Call Center

New account

New account

First name *
The field will be filled with letters (A to Z), who will be reflected at articles and comments
Last name *
The field will be filled with letters (A to Z), who will be reflected at articles and comments
Login *
The field will be filled with letters (A to Z) and/or numbers, without free spaces. Can be used the symbols, except the symbol _
E-mail *
The field will be completed with un valid e-mail. To this e-mail will be sent the confirmation link about the registred user account
Password *
The password will be contain at 5 to 15 characters and will be different for the date indicated at the login, name and firstname

Repeat password *

Cancel
Sign in

Sign in

Sign in can be to do with e-mail adresss or login

E-mail/Login *

Password *

Sig in with your Google account
MPass authentication
Cancel

Get the link to change the password

E-mail *

Send
Give up
EN
  • RO
  • RU
RORUEN
logo
About usDaily4The expert position 1Related sectionAccounting sector1Services16Contribuabil onest 2026Contacts

PP „Monitorul Fiscal FISC.MD”

MD-2005, Kishinev
Constantin Tanase street, no. 6
Inside „Fertilitatea-Chișinău” Corporation., 3-th floor, office 320

Antechamber:

022 822 024

E-mail:

secretariat@monitor.tax

Support and Contact Center:

022 822 024

You want to obtain an operative and complex answer?

Send your question and obtain the answer from the experts in the shortest time, at your e-mail or published in the compartment „Questions and answers”

Ask us a questionAcces disponibil doar pentru abonații Premium și Electronic. Asigură-te că ești autentificat în contul de utilizator și deții un abonament activ.
ArhivaFrequent questionsTerms and conditions of use of the page Privacy policyCookie PolicyMSG_COOKIE_PREFERENCES

Subscription at Newsline

facebooktwitterlinkedintelegraminstagramgoogle
MAIB logoMasterCard logoVisa logo

Site version: 1.0

Copyright 2026

All riths on the page monitorul.fisc.md belongs P.P. „Monitorul Fiscal FISC.MD”. Full or partial reproduction about informations or illustrations in either compartment is possible only with the written consent of the publication. Intellectual piracy is punishable by law.

icon

Feedback

To monitor the status of sent Feedback, initial we recommend to you to do sign in on the page. So, the answer at PP „Monitorul Fiscal FISC.md” at feedback will be save and will be displayed in your personal profile. If the feedback is sent an you aren't authentificated on the page, the message will be sent tot your e-mail.

E-mail: *

Message *
Message
0/500
Cancel the message
iconiconicon
icon
Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
  • Home page
  • Catalogul instituțiilor
  • Serviciul Fiscal de Stat
Banner A1
Banner A2

Availables services

For the command select the service you want from the category

icon

Subscribe

Premium
Classic
Electronic
icon

Trainings

instruire în săli
instruire online
icon

Library

cu livrare
fără livrare
Banner C3
Banner C4
Banner C5
Banner A1
Banner A2
icon

Advertising

tipar
electronică
img
icon

Search from the cathegory

Search in the category

The period of publication

at

to

Compartment page

Subcompartment page


Keyword

Present the results
Cancel

Serviciul Fiscal de Stat


Serviciul Fiscal de Stat

activitatea este direcţionată spre îndeplinirea sarcinilor principale – colectarea eficientă a veniturilor bugetare, asigurarea cadrului necesar aplicării unitare a legislaţiei fiscale, obţinerii unor performanţe în vederea asigurării stabilităţii. Serviciul Fiscal de Stat tinde să obţină un grad înalt de conformare voluntară a contribuabililor, oferindu-le soluţii optime şi competente printr-un ansamblu de servicii automatizate de o înaltă calitate, ce corespund ultimelor realizări din domeniul tehnologiilor informaţionale, concomitent cu armonizarea legislaţiei fiscale a Republicii Moldova la standardele internaţionale de administrare fiscală.

www.fisc.md

Privind modul de completare a dării de seamă CNOTAREX15

iconPrivind modul de completare a dării de seamă CNOTAREX15

Întru executarea şi administrarea prevederilor Capitolului 101 „Impozitarea notarilor publici” din titlul II al Codului fiscal nr. 1163-XIII din 24 aprilie 1997, a fost elaborat Ordinului Ministerului Finanţelor „Cu privire la aprobarea Formularul-tip al Calculului impozitului pe venitul persoanelor ce practică activitate profesională de notar sau executor judecătoresc şi modului de completare a acestuia” (Forma CNOTAREX15), nr. 72 din 25.05.2015 (MO nr. 131-138 din 29.05.2015).
24 September /2015 13:07

Veronica Vragaleva

Marina Cravcenco

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
Ion Prisăcaru: Recomandările Fondului Monetar Internațional stau la baza politicilor de reformare și modernizare a Serviciului Fiscal de Stat

Ion Prisăcaru: Recomandările Fondului Monetar Internațional stau la baza politicilor de reformare și modernizare a Serviciului Fiscal de Stat

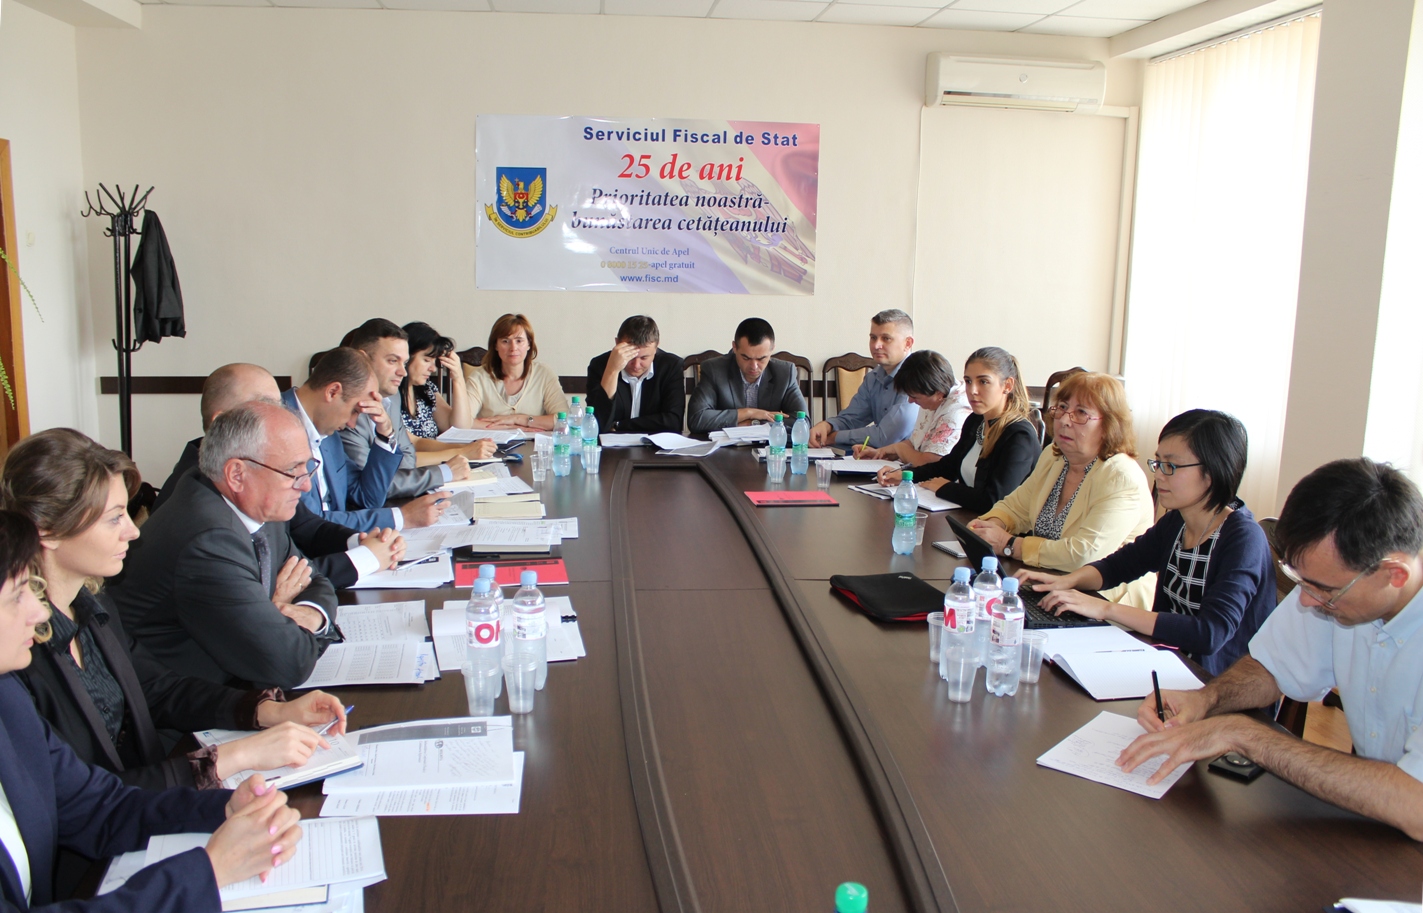
Recomandările Fondului Monetar Internațional stau la baza politicilor de reformare și modernizare a Serviciului Fiscal de Stat și apreciem mult, în acest sens, susținerea acordată de către FMI, a declarat Șeful SFS, Ion Prisăcaru, în cadrul întrevederii cu echipa Misiunii FMI, condusă de doamna Fah Jirasavetakul, Departamentul Afaceri Bugetar-Fiscale.

24 September /2015 12:30

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
Актуализирована Обобщенная база налоговой практики

Актуализирована Обобщенная база налоговой практики

Уважаемые налогоплательщики, сообщаем вам об очередном пополнении и актуализации Обобщенной базы налоговой практики.
23 September /2015 14:30

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
Приказ ГГНИ № 771 от 18.09.2015 об актуализации Обобщенной базы налоговой практики

Приказ ГГНИ № 771 от 18.09.2015 об актуализации Обобщенной базы налоговой практики

1. (29.1.11.9) Как следует применять положения ст.84 Налогового кодекса в случае, если экономический агент изменил режим по подоходному налогу в течение года (общий режим на режим IVAO или наоборот)? 2. (29.1.11.8) Считаются ли операционными доходами облагаемые 3% доходы в виде процентных начислений по банковским депозитам?

23 September /2015 14:29

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
Banner D1
10. (29.1.8.21) 	 Архив:  Какой налоговый режим (3% или 12%) применяют хозяйствующие субъекты, которые не получили доход от операционной деятельности по состоянию на 31 декабря года, предшествующего отчётному налоговому году?

10. (29.1.8.21) Архив: Какой налоговый режим (3% или 12%) применяют хозяйствующие субъекты, которые не получили доход от операционной деятельности по состоянию на 31 декабря года, предшествующего отчётному налоговому году?

В соответствии с положениями ч.(2) ст.541 Налогового кодекса, хозяйствующие субъекты, которые не являются плательщиками НДС по состоянию на 31 декабря налогового периода, предшествующего декларируемому налоговому периоду, получившие доход от операционной деятельности в сумме до 100 000 леев, применяют 3%-ный налоговый режим.
23 September /2015 14:27

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
9. (29.1.8.24) 	 Архив:  Какой налоговый Отчёт следует представить экономическому агенту, если он является субъектом налогообложения IVAO, находящимся в процессе ликвидации, учитывая, что форма (IVAO) не позволяет отражать все доходы и расходы, произведенные в процессе ликвидации?

9. (29.1.8.24) Архив: Какой налоговый Отчёт следует представить экономическому агенту, если он является субъектом налогообложения IVAO, находящимся в процессе ликвидации, учитывая, что форма (IVAO) не позволяет отражать все доходы и расходы, произведенные в процессе ликвидации?

В случае, если субъект налогообложения IVAO находится в процессе ликвидации, он применяет налоговый режим, установленный на момент начала ликвидации, и в срок, установленный в ч. (6) ст. 83 Налогового кодекса, должен представить Отчёт по налогу на доход от операционной деятельности (форма IVAO) без указания расходов и других доходов, отличных от указанных в Отчёте.
23 September /2015 14:25

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
8. (29.1.8.26) 	 Архив:  Какой налоговый режим применяем субъектом сектора малых и средних предприятий, который становится плательщиком НДС в течении налогового года?

8. (29.1.8.26) Архив: Какой налоговый режим применяем субъектом сектора малых и средних предприятий, который становится плательщиком НДС в течении налогового года?

В соответствии с разъяснениями Министерства финансов № 14/3-07/38 от 27.02.2012 г. и № 14/3-07/17 от 18.01.2013 г., если в течение периода, за который начисляется IVAO (квартал), хозяйствующие субъекты регистрируются в качестве плательщика НДС (добровольно или обязательно), тогда до момента регистрации – с первого дня месяца, следующего за месяцем, в течение которого было допущено превышение

23 September /2015 14:23

Facebook iconTwitter iconLinkedIn iconTelegram iconVK icon
icon
...11951196119711981199...